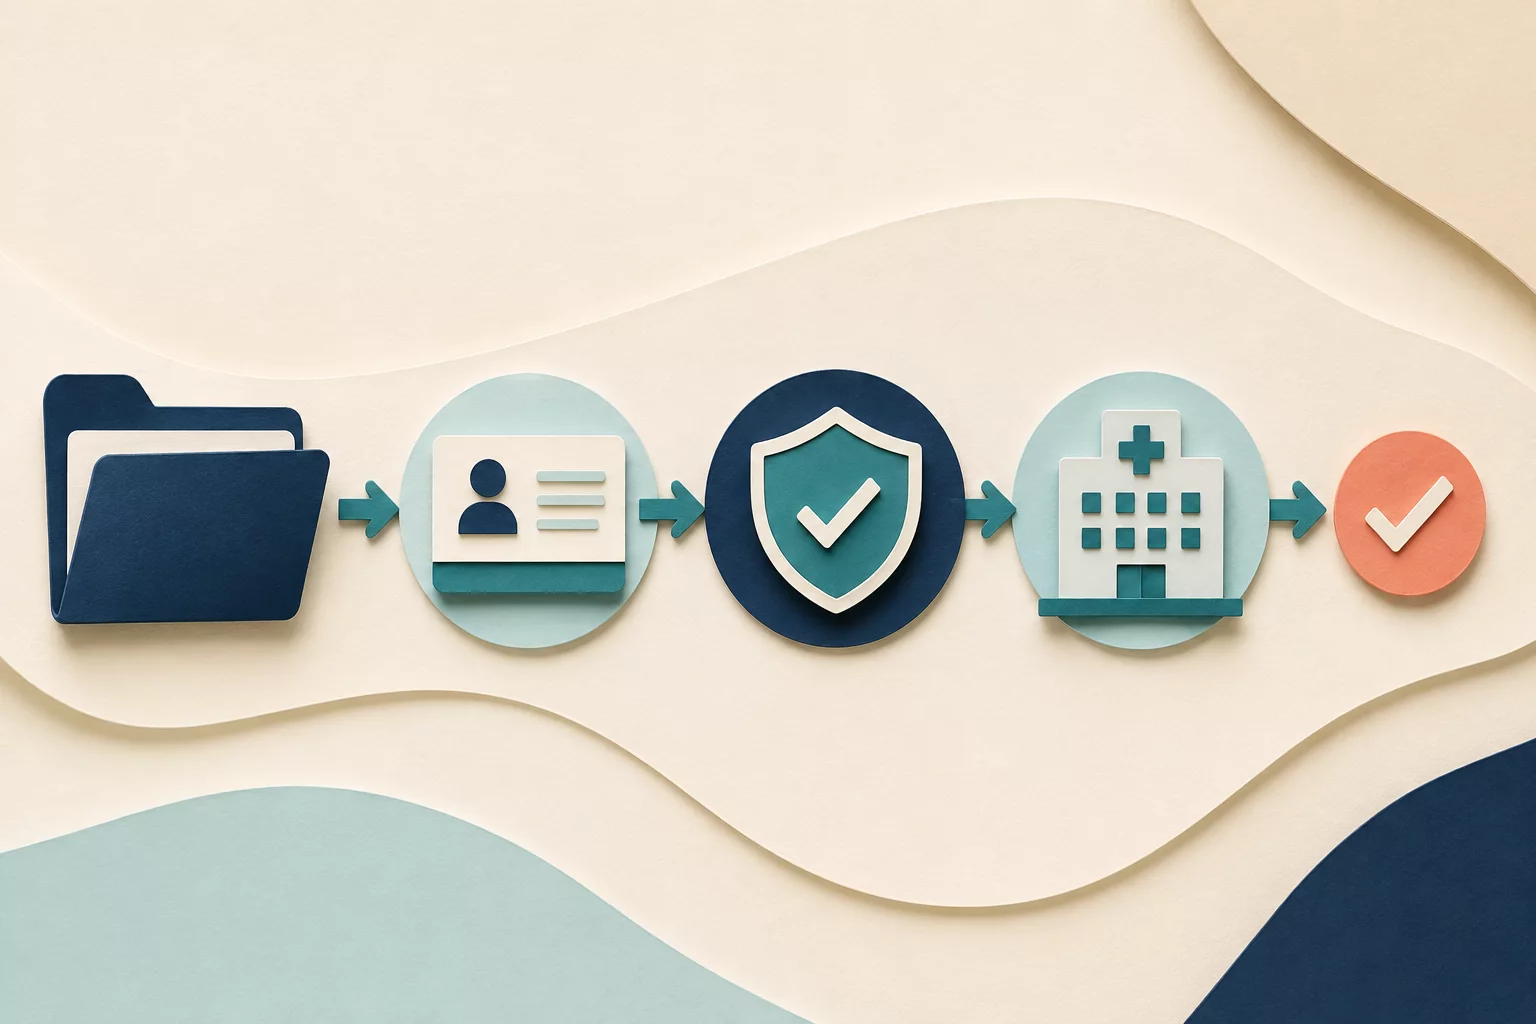
You hold a policy and something has come up, or you want to know whether the policy would respond if it did. This page is about using the cover rather than buying it: what happens when you claim, who pays whom, and what you pay yourself. If you are mid-claim, your insurer's claims line and your own policy guide outrank anything here. If the question is whether your cover would respond at all, or what excess and limits to carry next year, a broker can set several insurers' wordings side by side in one conversation; the form on this page puts you in touch with one that is FCA-authorised.
The search that brings most people here, how much can I claim back, assumes you pay the hospital and are reimbursed. On the wordings this site holds that is the exception: for hospital and specialist care the insurer settles with the provider, what you pay is the excess, and the "how much" is set by the limits on your certificate rather than by a reimbursement rate.
What this page answers
What actually happens when you claim, from the first call to the bill; how much the policy pays and how much is yours, which means the excess, any co-payment and the benefit limits read together; and whether claiming pushes up next year's premium, answered from the wording we hold rather than a figure we do not have. It does not tell you whether your claim will be paid. The full wording and your insurer decide that, and what follows are twelve extracts from six insurers' documents, not the documents. Nor is the premium something to claim back; it is the price of the year's cover, spent whether you claim or not, and the last question covers the tax position on it.
What happens when you claim
The sequence is the shape of the market rather than any one policy; your guide will have its own words for each step.
Something comes up, and you see a GP. Most policies route a claim through a GP referral to a specialist. Some open a direct route for particular conditions:
"If it's about: Cancer, Muscles, bones and joints, Mental health use our Direct Access service. This means you can call us about your symptoms without needing a referral from a GP."
— Bupa, Bupa By You policy guide (BINS 14718, 2024), page 6, read 4 September 2026.
You call the insurer before treatment is booked. This is the step people miss when they picture claiming as something done afterwards. On most UK policies the insurer approves the treatment, the specialist and the hospital before any of it happens, checking that the condition is covered, that the specialist and hospital are ones it recognises, and that waiting periods and limits allow it, and then gives an authorisation the hospital bills against. Have your policy number, what the GP said, and the specialist and hospital you have been given. Booking first and telling the insurer afterwards is the wrong way round, and what happens then is for your wording and your insurer, not this page.
The hospital or specialist bills the insurer, not you. This is where the claim-back picture breaks down. Bupa's guide works an example through:
"Helen has some physiotherapy which costs £250. We pay Helen's physiotherapist £150 and we'll let Helen know that she needs to pay the physiotherapist £100 (which is the policy excess). If Helen needs other treatment during the policy year, she doesn't need to pay another excess."
— Bupa, Bupa By You policy guide (BINS 14718, 2024), page 10, read 4 September 2026.
Helen does not pay £250 and reclaim £150. The insurer pays its share to the physiotherapist, tells Helen what she owes, and she pays that to the physiotherapist too. Freedom describes the same flow from the insurer's desk: "we will deduct this amount from the first valid invoice we receive and from any subsequent valid invoices until the excess has been fully applied. We will tell you when we have done this and you will then need to pay the excess amount to the relevant provider" (Freedom Health Insurance, Freedom Elite Policyholder's Guide to Cover, April 2025, page 31, read 4 September 2026). Nothing comes back to you because nothing left you, other than the excess, and on both wordings that goes to the clinic, not the insurer.
Some benefits are genuinely claimed back. The reimbursement picture is right for a narrower set, where you pay first and the insurer then pays you. AXA Health's handbook, on dental fees:
"We will pay for fees that you have paid directly to a dentist or dental hygienist, so long as they are registered with the General Dental Council"
— AXA Health, Personal Health membership handbook (October 2024), page 30, read 4 September 2026.
Fees you have paid, then the insurer pays: that is a claim back, and the one place the receipt matters. Your guide will say which benefits work this way and the time limit for sending them in; we have not established those terms for any insurer here.
What named insurers actually say about what you pay
Three mechanisms decide what is yours: the excess is a first slice, a co-payment is a share, a limit is a ceiling. The clauses below are extracts, so they show how each insurer words the mechanism, not everything that insurer's policy does.
The excess: a first slice, charged against the bill
"Benefits covered under this policy will be subject to an excess payable for each member every policy year."
— Aviva, Healthier Solutions terms and conditions (April 2025 issue), page 11, read 4 September 2026.
The same page lists six levels, £100, £200, £500, £1,000, £3,000 and £5,000, each person on the policy carrying their own. Bupa's example shows the other half: once Helen has paid her £100, "she doesn't need to pay another excess" that policy year. And not every contact with the insurer starts the excess:
"If you have a Direct Access phone or video assessment you won't need to pay an excess for it and the cost won't be subtracted from your outpatient benefit allowance (if either of these apply to your policy)."
— Bupa, Bupa By You policy guide (BINS 14718, 2024), page 7, read 4 September 2026.
Whether your excess runs per policy year or per claim is the most useful thing to know before you ring, and it is on your certificate. The site's page on how the health insurance excess works goes through it in detail.
A co-payment: a share of every bill
"Where an excess is chosen, you must pay your excess for eligible treatment up to your chosen level per Policy year before we provide benefit. Where Shared Responsibility (co-payment) has been selected, you must pay 25% of claims for eligible treatment up to your chosen level of Shared Responsibility."
— WPA, Complete Health Insurance Product Information Document (November 2025), page 2, read 4 September 2026.
Under the co-payment you pay a quarter of each eligible bill from the first pound until your contributions reach the ceiling you chose, rather than the whole of each bill until a fixed level is spent. It is the only percentage co-payment in the documents we hold; we have not established whether other insurers offer one.
Limits: the ceiling on "how much"
The pound figure people are looking for is usually a benefit limit, and it usually sits on out-patient cover:
"Out-patient Treatment Consultations with a Specialist – £250 (increase with the Extra Out-patient Consultations Optional Extra)"
— WPA, Complete Health Insurance Product Information Document (November 2025), page 1, read 4 September 2026.
On that wording, £250 a policy year is the most the policy pays towards seeing a specialist as an out-patient unless the optional extra was bought. A lower out-patient limit can also change what the policy responds to, not only how much:
"If you have chosen a reduced out-patient limit of £500 or £1,000 you are not covered as an in-patient, day-patient, or out-patient for treatment for: complications of pregnancy and childbirth, or surgical procedures on the teeth performed in a hospital"
— Aviva, Healthier Solutions terms and conditions (April 2025 issue), page 8, read 4 September 2026.
So what you can claim is eligible treatment, up to the limit for that category on your certificate, less your excess or co-payment, and nothing for what the limit you chose switched off. The figure is on your schedule; the wording behind it is in the guide.
The first fortnight, and a second opinion
"A 14 day deferment period applies to any symptom(s) or condition(s), whether diagnosed or not, which arise in the first 14 days of your Policy commencing, unless declared to and accepted in writing by WPA."
— WPA, Complete Health Insurance Product Information Document (November 2025), page 1, read 4 September 2026.
Waiting periods differ by insurer and by benefit; the site's page on private health insurance waiting periods sets them out. A claim can also go further than you expected: AXA Health's handbook says that if you want a second opinion "we will help you find an alternative specialist we'll pay in full" (AXA Health, Personal Health membership handbook, October 2024, page 10, read 4 September 2026).
Five insurers, five ways of wording the same three mechanisms, and your certificate says which apply to you. If reading your schedule against these clauses leaves you unsure what you are carrying into next year, a broker can show how two or three of these wordings would have handled the claim you have just made, and what each costs to carry. The form on this page puts you in touch, and there is no charge for asking.
Common questions
How much can you claim on private health insurance?
There is no single figure. The policy pays for eligible treatment up to the limit for that category on your certificate, less any excess or co-payment; on the wordings we hold the pound limits tend to sit on out-patient cover, as with WPA's £250 cap on specialist consultations. For hospital treatment the insurer usually settles the bill directly, so the question is less how much you get back than what the limit and your excess are.
Does claiming on health insurance increase the premium, and by how much?
We hold no premium data, so we cannot say by how much, and no clause we hold says a claim raises the price. What we do hold is The Exeter's product document, which lists "A No Claims Discount, where you'll earn discounts on your premiums if you stay healthy and don't claim" (The Exeter, Health+ Insurance Product Information Document, October 2025, page 1, read 4 September 2026), so on a policy with that feature a claim can cost you a discount at renewal. Whether yours has one is in your schedule and renewal notice; the site's page on no-claims discounts on health insurance covers it.
Can I claim health insurance premiums on my taxes?
This is a tax question rather than an insurance one, and we hold no HMRC guidance behind this page, so treat this as the general position to check rather than a ruling. For an individual paying for their own policy out of taxed income there is no relief to claim, and where an employer pays, the cover is usually treated as a taxable benefit in kind. If you are self-employed or the policy is paid through a company, ask an accountant or HMRC before assuming either way.
Nothing here replaces the call to your insurer if you are mid-claim. But if what the page has really raised is next year's policy, which excess, whether a co-payment would suit you better, how much out-patient limit to carry, fill in the form on this page and a broker can put several insurers' current wordings in front of you. It is free and takes a few minutes.